Read the threshold and comparator together
Read the word beside the number: it changes the day you cross the line. More than a number means the number itself is still below that day-test line. At least a number includes the number itself. Two rows displaying the same number can therefore have different crossing dates.
The table gives you the threshold, comparison, day rule and confidence side by side. It includes every state and District of Columbia in the bundled rule set. Rows marked approximate retain that label visibly. They may have a month-based expression, an unstated day convention, or another part of the rule that cannot be reduced to a precise presence-day counter.
Do not convert a month expression into a guessed number of days. Months differ in length, and a rule about time maintaining an abode asks something different from a rule about days physically present. A row with no presence-day test is not a zero-day threshold. It means this table has no such line to count against for that jurisdiction.
Example: Jordan’s New York days
Example: Jordan’s travel diary records presence in New York on every date from 1 January through 2 July 2026. That is 183 calendar dates. The New York row uses more than 183 days, so 183 itself has not crossed that day-test line. Add presence on 3 July and the total becomes 184, which is above it.
New York's day convention is any part of a day. An arrival late on 2 July still contributes that date in the simple presence count. Adding hours instead, or keeping only overnight stays, would answer a different question and could change the number near the line.
The row also sits within a wider state-residency rule involving a permanent place of abode. Use Jordan’s diary to compare the days. You’ll also need to check the permanent-place-of-abode condition separately; a hotel booking or location record doesn’t establish it.
Build a diary before comparing state totals
Use dated records that show where you were, including travel days and short visits. If a state's convention counts any presence, a single date can contribute to more than one state. That makes the sum of state totals a different quantity from the number of elapsed calendar days in the year.
Keep the tax-year boundaries visible when reviewing a total. Moving an itinerary to another year changes which dates contribute to that year's count. The state table is about state presence rules; it should not be substituted for a US admission timeline or a federal physical-presence formula.
The confidence label tells you how precisely the rule can be counted; you still need to check your own circumstances. An exact day convention still leaves other tests outside the count. For an approximate row, read the linked source before planning around that number. Each state name in the table links to its source list below.
How Passport Days counts it
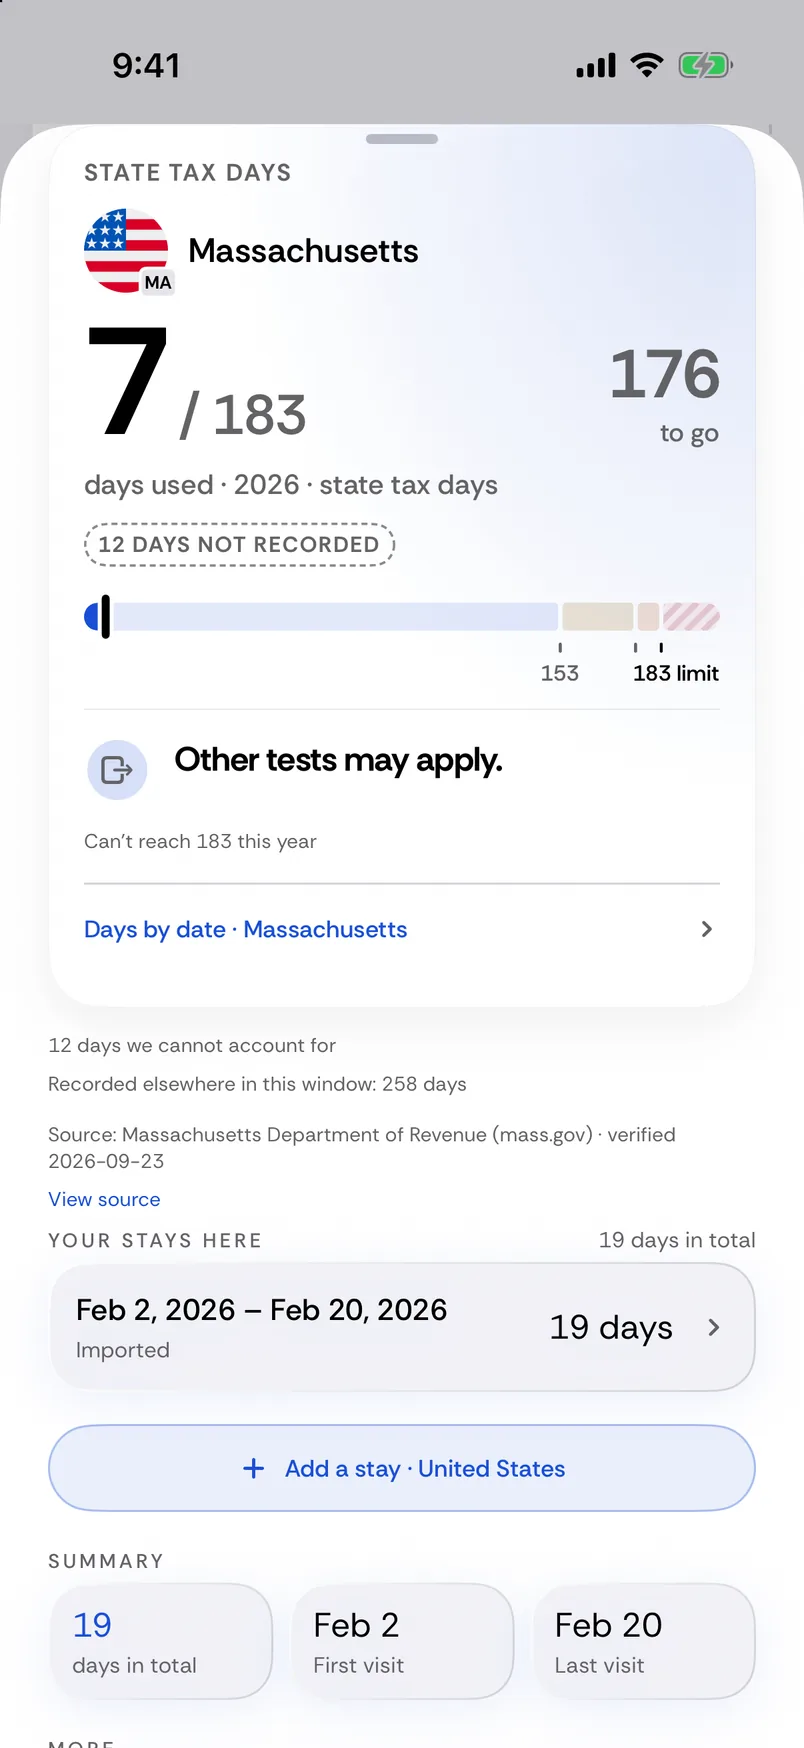
Passport Days keeps state presence separate from country stays and uses the bundled state rule for its counter. The state view tracks dates and presents the threshold where the pack has a reducible day test. Domicile, permanent-place-of-abode conditions and other factual tests are separate from that arithmetic. The table here uses those same rules, so you see the same thresholds, comparisons, day conventions and confidence labels as the app.
Let Passport Days do this
Keep the count on your iPhone, with your trips already there. Counters and automatic tracking are Premium.
See each state’s own count
Track days in each US state and DC, with that state’s tax year and day threshold where one exists.
Record travel as you go
Automatic tracking records your country and US state. Review your records and fill any gaps.
Share your travel history
Export CSV or a PDF summary to review the dates behind your count.
State presence-day table
| State | Threshold / expression | Comparator | Day rule | Confidence |
|---|---|---|---|---|
| Alabama | 7 calendar months; no fixed day test | More than; not converted to days | Not stated in the pack | approximate |
| Alaska | No broad personal income tax day test | No presence-day test | Not stated in the pack | approximate |
| Arizona | 9 calendar months; no fixed day test | More than; not converted to days | Not stated in the pack | approximate |
| Arkansas | 6 calendar months; no fixed day test | More than; not converted to days | Not stated in the pack | approximate |
| California | 9 calendar months; no fixed day test | More than; not converted to days | Not stated in the pack | approximate |
| Colorado | 6 calendar months; no fixed day test | More than; not converted to days | Not stated in the pack | approximate |
| Connecticut | 183 days | More than (>) | Any part of a day | exact |
| Delaware | 183 days | More than (>) | Not stated in the pack | approximate |
| District of Columbia | Abode-duration test; no presence-day threshold | No presence-day test | Not stated in the pack | approximate |
| Florida | No broad personal income tax day test | No presence-day test | Not stated in the pack | approximate |
| Georgia | 183 days | At least (≥) | Any part of a day | approximate |
| Hawaii | 200 days | More than (>) | Not stated in the pack | approximate |
| Idaho | 270 days | More than (>) | Any part of a day | exact |
| Illinois | 9 calendar months; no fixed day test | More than; not converted to days | Not stated in the pack | approximate |
| Indiana | 183 days | More than (>) | Not stated in the pack | approximate |
| Iowa | 183 days | More than (>) | Not stated in the pack | approximate |
| Kansas | 6 calendar months; no fixed day test | More than; not converted to days | Any part of a day | approximate |
| Kentucky | 183 days | More than (>) | Not stated in the pack | approximate |
| Louisiana | 6 calendar months; no fixed day test | More than; not converted to days | Not stated in the pack | approximate |
| Maine | 183 days | More than (>) | Any part of a day | exact |
| Maryland | 183 days | At least (≥) | Any part of a day | approximate |
| Massachusetts | 183 days | More than (>) | Any part of a day | exact |
| Michigan | 183 days | At least (≥) | Not stated in the pack | approximate |
| Minnesota | 183 days | At least (≥) | Any part of a day | approximate |
| Mississippi | No day threshold; facts and circumstances | No presence-day test | Not stated in the pack | exact |
| Missouri | 183 days | More than (>) | Not stated in the pack | approximate |
| Montana | No day threshold; facts and circumstances | No presence-day test | Not stated in the pack | exact |
| Nebraska | 183 days (6-month expression) | At least (≥) | Any part of a day | approximate |
| Nevada | No broad personal income tax day test | No presence-day test | Not stated in the pack | approximate |
| New Hampshire | No broad personal income tax day test | No presence-day test | Not stated in the pack | approximate |
| New Jersey | 183 days | More than (>) | Not stated in the pack | approximate |
| New Mexico | 185 days | At least (≥) | Not stated in the pack | approximate |
| New York | 183 days | More than (>) | Any part of a day | exact |
| North Carolina | 183 days | More than (>) | Not stated in the pack | approximate |
| North Dakota | 210 days (7-month expression) | More than (>) | Not stated in the pack | approximate |
| Ohio | Contact-period test; no calendar-day threshold | No presence-day test | Any part of a day | approximate |
| Oklahoma | 7 calendar months; no fixed day test | More than; not converted to days | Not stated in the pack | approximate |
| Oregon | 200 days | More than (>) | Any part of a day | exact |
| Pennsylvania | 183 days | More than (>) | Any part of a day | exact |
| Rhode Island | 183 days | More than (>) | Any part of a day | exact |
| South Carolina | No day threshold; facts and circumstances | No presence-day test | Not stated in the pack | exact |
| South Dakota | No broad personal income tax day test | No presence-day test | Not stated in the pack | approximate |
| Tennessee | No broad personal income tax day test | No presence-day test | Not stated in the pack | approximate |
| Texas | No broad personal income tax day test | No presence-day test | Not stated in the pack | approximate |
| Utah | Day count is a domicile factor; no standalone day test | No presence-day test | Not stated in the pack | approximate |
| Vermont | 183 days | More than (>) | Not stated in the pack | approximate |
| Virginia | 183 days | More than (>) | Any part of a day | approximate |
| Washington | No broad personal income tax day test | No presence-day test | Any part of a day | approximate |
| West Virginia | 183 days | More than (>) | Any part of a day | exact |
| Wisconsin | No day threshold; facts and circumstances | No presence-day test | Not stated in the pack | exact |
| Wyoming | No broad personal income tax day test | No presence-day test | Not stated in the pack | approximate |
Questions
Is 183 days the same line in every state?
No. States use different thresholds and tests. Read the comparator, day convention and confidence beside each expression.
What is the difference between more than and at least?
More than 183 starts above 183. At least 183 includes 183 itself. The comparator changes which total reaches the line.
Does no day test mean no other residency test?
No. A row without a presence-day threshold may still use domicile, facts and circumstances, an abode-duration test or another measure.
What does approximate mean in the table?
The bundled rule is not represented as a fully exact day count. Read its source list and retain any month-based expression or unstated day convention.
Sources
Alabama
Alaska
Arizona
- Arizona Administrative Code, Title 15, Chapter 2: Department of Revenue, Income and Withholding Tax Section — Arizona Secretary of State, Administrative Rules Division
- Arizona Form 140, 2025 Resident Personal Income Tax Return: instructions — Arizona Department of Revenue
- Arizona Form 140NR, 2025 Nonresident Personal Income Tax Return: instructions — Arizona Department of Revenue
- Arizona Form 140PY, 2025 Part-Year Resident Personal Income Tax Return: instructions — Arizona Department of Revenue
- Individual Income Tax Information — Arizona Department of Revenue
- Arizona Individual Income Tax Procedure ITP 92-1, Procedure for Determining Residency Status — Arizona Department of Revenue
- Pub 704, Taxpayers in the Military — Arizona Department of Revenue
- A.R.S. § 1-215. Definitions — Arizona State Legislature
- A.R.S. § 43-104. Definitions — Arizona State Legislature
Arkansas
- 26 CAR § 100-113. Definitions — Arkansas Code § 26-51-102 — Arkansas Secretary of State, Code of Arkansas Rules
- 2025 AR1000F and AR1000NR Instructions — Arkansas Department of Finance & Administration
- Comprehensive Individual Income Tax Regulations — Arkansas Department of Finance & Administration, Revenue Division
California
- 2025 Instructions for Form 540NR, Nonresident or Part-Year Resident Booklet — California Franchise Tax Board
- FTB Publication 1031 — California Franchise Tax Board
- Residency and Sourcing Technical Manual — California Franchise Tax Board
- Revenue and Taxation Code § 17014 — California Legislature
- Revenue and Taxation Code § 17016 — California Legislature
Colorado
- 1 CCR 201-2 INCOME TAX, current version effective 03/02/2026 — Colorado Department of Revenue, Taxation Division
- Colorado Individual Income Tax Glossary — Colorado Department of Revenue, Taxation Division
- Colorado Individual Income Tax Guide — Colorado Department of Revenue, Taxation Division
- Income Tax Topics: Part-Year Residents & Nonresidents — Colorado Department of Revenue, Taxation Division
- Colorado Revised Statutes 2024 Uncertified Printout, Title 39, 39-22-103 — Colorado Office of Legislative Legal Services
Connecticut
- Conn. Gen. Stat. § 12-701(a)(1)-(3) and — Connecticut General Assembly
- IP 2019(5), Connecticut Income Tax Information for Armed Forces Personnel and Veterans — Connecticut Department of Revenue Services
- DRS web page 'Tax Information' — Connecticut Department of Revenue Services
- SN 2000(17), 2000 Legislation Affecting the Connecticut Income Tax — Connecticut Department of Revenue Services
- Regs. Conn. State Agencies § 12-701(a)(1)-1 Resident of this state — Connecticut Department of Revenue Services
Delaware
- Delaware Administrative Code — State of Delaware, Registrar of Regulations
- 30 Del. C. § 1103 Resident individual defined — State of Delaware, Delaware Code Online
- 2025 Delaware Individual Income Tax Return, Resident Instructions — Delaware Division of Revenue
- Technical Information Memorandums — Delaware Division of Revenue
District of Columbia
Florida
Georgia
Hawaii
- Hawaii Administrative Rules Title 18 Chapter 235 — State of Hawaii Department of Taxation
- Hawaii Revised Statutes §235-1 Definitions — Hawaii State Legislature
- HRS Chapter 235 Income Tax Law — State of Hawaii Department of Taxation
- Letter Ruling No. 2021-01 — State of Hawaii Department of Taxation
- 2025 Form N-11 Instructions — State of Hawaii Department of Taxation
- 2025 Form N-15 Instructions — State of Hawaii Department of Taxation
- Tax Information Release No. 90-3 — State of Hawaii Department of Taxation
- Tax Information Release No. 97-1, Determination of Residence Status — State of Hawaii Department of Taxation
Idaho
- Idaho Code 63-3013 Resident; Internet Archive snapshot 20260906192235 — Idaho State Legislature
- Idaho Code 63-3013A Part-year resident; Internet Archive snapshot 20260414212359 — Idaho State Legislature
- IDAPA 35.01.01 Income Tax Administrative Rules, current PDF — Idaho Division of Financial Management, Office of the Administrative Rules Coordinator / Idaho State Tax Commission
- Individual Income Tax Forms and Instructions — Idaho State Tax Commission
Illinois
- 2025 Form IL-1040 Instructions — Illinois Department of Revenue
- 86 Ill. Adm. Code 100.3020 Resident — Illinois General Assembly, Joint Committee on Administrative Rules
- Who is an Illinois resident? — Illinois Department of Revenue
- IT 13-0008-GIL, 06/27/2013, Residency/Nonresidency — Illinois Department of Revenue
- Publication 102, Illinois Filing Requirements for Military Personnel — Illinois Department of Revenue
- Pub-119, Illinois Schedule NR for Individuals — Illinois Department of Revenue
- Publication 130, Who is Required to Withhold Illinois Income Tax — Illinois Department of Revenue
- Schedule NR IL-1040 Instructions 2025 — Illinois Department of Revenue
- First-Time Filer Residency Information — Illinois Department of Revenue
Indiana
Iowa
Kansas
Kentucky
- 2025 Kentucky Individual Income Tax Forms Instruction Packet — Kentucky Department of Revenue
- 2025 Kentucky Income Tax Return Nonresident or Part-Year Resident Instruction Packet, Form 42A740-NP(P) — Kentucky Department of Revenue
- Final Ruling No. 2014-41 — Kentucky Department of Revenue
- 103 KAR 17:010. Residence. — Kentucky Department of Revenue
- 103 KAR 17:010. Residence. — Kentucky Legislative Research Commission
- 103 KAR 17:140. Individual income tax - reciprocity - nonresidents. — Kentucky Legislative Research Commission / Kentucky Department of Revenue
- KRS 141.010 Definitions for chapter for taxable years beginning on or after January 1, 2018 — Kentucky Legislative Research Commission
- KRS 141.175 Extension for members of Armed Forces serving in combat zones — Kentucky Legislative Research Commission
Louisiana
- Louisiana Administrative Code, Title 61 — Louisiana Office of the State Register
- FAQ: How can I resolve a bill for individual income tax for a year that I was not a Louisiana resident? — Louisiana Department of Revenue
- 2025 Louisiana Resident Income Tax Return instructions — Louisiana Department of Revenue
- La. R.S. 47:31 - Individuals, corporations, and trusts subject to tax — Louisiana State Legislature
Maine
- Determining Residency Status - Guidance Document — Maine Revenue Services, Income/Estate Tax Division
- Residency Safe Harbors for Residents Spending Time Outside Maine - Guidance Document — Maine Revenue Services, Income/Estate Tax Division
- 36 M.R.S. § 5102(5) Resident individual — Maine Legislature, Office of the Revisor of Statutes
- Chapter 807: Residency — Maine Secretary of State
Maryland
- Maryland Income Tax Administrative Release No. 37, Subject: Domicile and Residency — Comptroller of Maryland, Revenue Administration Division
- COMAR 03.04.02.01 Definitions — Maryland Division of State Documents
- 2025 Maryland Nonresident Income Tax Return Instructions — Comptroller of Maryland
- 2025 Maryland State & Local Tax Forms & Instructions — Comptroller of Maryland
- Fiscal and Policy Note, 2025 Session, Senate Bill 59 — Maryland General Assembly, Department of Legislative Services
- Annotated Code of Maryland, Tax-General Article, §10-101 — Maryland General Assembly
Massachusetts
- 830 CMR 62.5A.1: Non-Resident Income Tax, subsection — Massachusetts Department of Revenue
- Directive 21-1: Personal Income Tax Guidance for Employees who Telecommuted in 2020 due to the COVID-19 State of Emergency — Massachusetts Department of Revenue
- Legal and Residency Status in Massachusetts — Massachusetts Department of Revenue
- 2025 Form 1 Instructions — Massachusetts Department of Revenue
- 2025 Form 1-NR/PY Instructions — Massachusetts Department of Revenue
- Letter Ruling 08-11: Taxpayer Domiciled in New York, Resident in Massachusetts — Massachusetts Department of Revenue
- Letter Ruling 09-5: Residency — Massachusetts Department of Revenue
- Massachusetts General Laws, Part I, Title IX, Chapter 62, Section 1: Definitions — paragraphs — The General Court of the Commonwealth of Massachusetts
- TIR 20-15: Revised Guidance on the Massachusetts Tax Implications of an Employee Working Remotely due to the COVID-19 Pandemic — Massachusetts Department of Revenue
- TIR 95-7: Change in the Definition of "Resident" for Massachusetts Income Tax Purposes — Massachusetts Department of Revenue
Michigan
Minnesota
- 183-Day Rule — Minnesota Department of Revenue
- Active-Duty Residency — Minnesota Department of Revenue
- Income Tax Fact Sheet 1, Residency — Minnesota Department of Revenue
- 2025 Minnesota Individual Income Tax Forms and Instructions, Form M1 — Minnesota Department of Revenue
- Part-Year Residents — Minnesota Department of Revenue
- Minnesota Rules, part 8001.0300 Resident and domicile defined; considerations — Minnesota Office of the Revisor of Statutes
- Minnesota Statutes 2025, section 290.01 — Minnesota Office of the Revisor of Statutes
Mississippi
Missouri
Montana
Nebraska
- Title 316 NAC Chapter 22 — Nebraska Department of Revenue
- Neb. Rev. Stat. § 77-2714.01 - Terms, defined — Nebraska Legislature
- 2025 Nebraska Individual Income Tax Booklet — Nebraska Department of Revenue
- Determining Residency Status for Nebraska Individual Income Tax Filing, Information Guide 8-645-2008 Rev. 5-2019 — Nebraska Department of Revenue
New Hampshire
- Interest & Dividends Tax Frequently Asked Questions — New Hampshire Department of Revenue Administration
- Interest & Dividends Tax — New Hampshire Department of Revenue Administration
- N.H. Admin. Rules Rev 900 — New Hampshire Department of Revenue Administration
- RSA Chapter 77 Taxation of Incomes — New Hampshire General Court
New Jersey
- Form NJ-1040 Instructions, tax years 2018, 2019, 2020, 2021, 2022, 2023, 2024 — New Jersey Department of the Treasury, Division of Taxation
- 2025 Form NJ-1040 Instructions — New Jersey Department of the Treasury, Division of Taxation
- 2019 Form NJ-1040NR Instructions — New Jersey Department of the Treasury, Division of Taxation
- 2025 Form NJ-1040NR Instructions — New Jersey Department of the Treasury, Division of Taxation
- GIT-6 Part-Year Residents and Nonresidents — New Jersey Department of the Treasury, Division of Taxation
- Income Tax - Nonresidents — New Jersey Department of the Treasury, Division of Taxation
- N.J.S.A. 54A:1-2 Definitions — New Jersey Legislature, Office of Legislative Services
- N.J.S.A. 54A:8-8 Definitions relative to payment of estimated gross income tax on real property sales by nonresidents — New Jersey Legislature, Office of Legislative Services
New Mexico
- 3.3.1 NMAC, §§ 3.3.1.7 DEFINITIONS and 3.3.1.9 RESIDENCY — New Mexico Taxation and Revenue Department
- 2025 PIT-1 New Mexico Personal Income Tax instructions — New Mexico Taxation and Revenue Department
- Income Tax Act, Sections 7-2-1 to 7-2-41 NMSA 1978, with Regulations [3.3 NMAC] — New Mexico Taxation and Revenue Department
New York
- Matter of John and Janine Zanetti, DTA No. 824337 — NYS Division of Tax Appeals
- IT-203-I — NYS Department of Taxation and Finance
- Nonresident Audit Guidelines — NYS Department of Taxation and Finance, Income Franchise Field Audit Bureau
- Frequently Asked Questions about Filing Requirements, Residency, and Telecommuting for New York State Personal Income Tax — NYS Department of Taxation and Finance
- Income tax definitions — NYS Department of Taxation and Finance
- NY Tax Law §605 General provisions and definitions — New York State Senate
- Tax Bulletin IT-690 Permanent Place of Abode — NYS Department of Taxation and Finance
- Advisory Opinion TSB-A-06(6)I / TSB-A-06(4)M — NYS Department of Taxation and Finance
- TSB-M-18(4)I Summary of Personal Income Tax Changes Enacted in the 2018-2019 Budget Bill — NYS Department of Taxation and Finance
North Carolina
- Form D-401, North Carolina Individual Income Tax Instructions for tax year 2025 — North Carolina Department of Revenue
- 2025 Personal Taxes Bulletin — North Carolina Department of Revenue, Personal Taxes Division
- N.C. Gen. Stat. § 105-153.3 Definitions — North Carolina General Assembly
- Archived versions of G.S. 105-153.3 used to check whether subdivision — North Carolina General Assembly; Internet Archive snapshots 20150919022113
- N.C. Gen. Stat. Chapter 105, Article 4 Income Tax — North Carolina General Assembly; Internet Archive snapshot 20260215202827
- 17 NCAC 06B .3902 NONRESIDENTS and 17 NCAC 06B .3903 PART-YEAR RESIDENT — North Carolina Office of Administrative Hearings, North Carolina Administrative Code
- 17 NCAC Chapter 06 Subchapter B — North Carolina Office of Administrative Hearings, North Carolina Administrative Code
North Dakota
- N.D. Admin. Code ch. 81-03-02.2, §§ 81-03-02.2-01 and -01.1 — North Dakota Office of State Tax Commissioner
- 2025 North Dakota Individual Income Tax booklet, Forms ND-EZ / ND-1 — North Dakota Office of State Tax Commissioner
- N.D.C.C. ch. 57-38 — North Dakota Legislative Branch
- Resident — North Dakota Office of State Tax Commissioner
Ohio
- FAQs: Income - Ohio Residency and Residency Credits — Ohio Department of Taxation
- Income Tax Information Release IT 2018-01 – Residency Guidelines - Tax Imposed on Resident and Nonresident Individuals for Taxable Years 2018 and Forward — Ohio Department of Taxation
- 2025 Ohio IT 1040 / SD 100 Individual and School District Income Tax Instructions — Ohio Department of Taxation
- What Does Ohio Residency Mean for Taxes? — Ohio Department of Taxation
- Ohio Revised Code 5747.24 'Presumption of domicile.' Effective: September 13, 2018; Latest Legislation: House Bill 292 - 132nd General Assembly — Ohio Legislative Service Commission
Oklahoma
Oregon
- What form do I use? : Individuals — Oregon Department of Revenue
- OAR 150-316-0025 Definition: “Resident” — Oregon Secretary of State, Archives Division
- 2025 Oregon Publication OR-17, Individual Income Tax Guide, 150-101-431 — Oregon Department of Revenue
- 2025 Oregon Form OR-40 Instructions — Oregon Department of Revenue
- 2025 Oregon Income Tax Form OR-40-N and Form OR-40-P Instructions, 150-101-048-1 — Oregon Department of Revenue
- Oregon Revised Statutes, Chapter 316 — Oregon State Legislature, Legislative Counsel Committee
Pennsylvania
- 61 Pa. Code § 101.1. Definitions. — Pennsylvania Legislative Reference Bureau
- 61 Pa. Code § 101.3. Domicile. — Pennsylvania Legislative Reference Bureau
- 61 Pa. Code § 101.5. Rules for days within and without this Commonwealth — Pennsylvania Legislative Reference Bureau
- Determining Residency — Pennsylvania Department of Revenue
- Personal Income Tax Preparation Guide for PA-40, DFO-02 — Pennsylvania Department of Revenue
- PA Personal Income Tax Guide – Brief Overview and Filing Requirements, DSM-12 — Pennsylvania Department of Revenue
- PA Personal Income Tax Guide – Brief Overview and Filing Requirements — Pennsylvania Department of Revenue
- Tax Reform Code of 1971, Act of Mar. 4, 1971, P.L. 6, No. 2 — Pennsylvania General Assembly
Rhode Island
South Carolina
- S.C. Code § 12-6-510 — South Carolina Legislative Services Agency
- A Guide to Determining a Taxpayer's Domicile for Income Tax Purposes, First Edition - June 2021 — South Carolina Department of Revenue, Policy Division
- Information about H. 4216 — South Carolina Department of Revenue
- H. 4216 — South Carolina Legislature
South Dakota
Tennessee
- Hall Income Tax — Tennessee Department of Revenue
- Hall Income Tax Manual — Tennessee Department of Revenue
- Hall Income Tax Manual — Tennessee Department of Revenue
- 2017 Public Chapter No. 181 — Tennessee Secretary of State
- Rules of Department of Revenue, Chapter 1320-3-2 Income Tax Rules — Tennessee Secretary of State
- Senate Joint Resolution 1 — Tennessee General Assembly
Utah
Vermont
Virginia
- Code of Virginia § 58.1-302. Definitions — Commonwealth of Virginia, Division of Legislative Automated Systems
- Code of Virginia § 58.1-303. Residency for portion of tax year — Commonwealth of Virginia, Division of Legislative Automated Systems
- Code of Virginia § 58.1-321. Exemptions and exclusions — Commonwealth of Virginia, Division of Legislative Automated Systems
- Ruling of the Tax Commissioner, P.D. 00-68 — Virginia Department of Taxation
- Ruling of the Tax Commissioner, P.D. 11-177 — Virginia Department of Taxation
- Ruling of the Tax Commissioner, P.D. 15-99 — Virginia Department of Taxation
- Ruling of the Tax Commissioner, P.D. 17-118 — Virginia Department of Taxation
- Ruling of the Tax Commissioner, P.D. 98-183 — Virginia Department of Taxation
- 2025 Form 760 Resident Individual Income Tax Instructions — Virginia Department of Taxation
- 2025 Form 760PY Part-Year Resident Instructions — Virginia Department of Taxation
- 2025 Form 763 Non-Resident Individual Income Tax Instructions — Virginia Department of Taxation
- Military Tax Tips — Virginia Department of Taxation
- Residency Status — Virginia Department of Taxation
- Website Disclaimer — Virginia Department of Taxation
- 23VAC10-110-130. Exemptions and exclusions — Commonwealth of Virginia, Division of Legislative Automated Systems
- 23VAC10-110-30. Definitions — Commonwealth of Virginia, Division of Legislative Automated Systems
Washington
- Washington State Constitution, Art. VII, Sec. 1 — Washington State Legislature
- Income tax — Washington State Department of Revenue
- RCW 1.90.100 Personal income tax prohibition — Washington State Legislature
- RCW 82.87.020 Definitions — Washington State Legislature
- Chapter 82A.04 RCW — Washington State Legislature
- ESSB 6346, Chapter 238, Laws of 2026 — Washington State Legislature
- WAC 458-20-301 Capital gains excise tax—Definitions, deductions, exemptions, and allocation of gains and losses — Washington State Legislature
West Virginia
Wisconsin
- Wis. Admin. Code Tax 2.01 Residence; Tax 2.02 Reciprocity — Wisconsin Legislature
- 2025 Form 1NPR Instructions — Wisconsin Department of Revenue
- Legal Residence/Domicile — Wisconsin Department of Revenue
- Publication 122 — Wisconsin Department of Revenue
- Wis. Stat. s. 71.02 Imposition of tax — Wisconsin Legislature
- Wis. Stat. ch. 71 Income and franchise taxes — Wisconsin Legislature